Selecting Multifamily Markets for the Next Cycle
Jul 2026
View available investments in your area

Sorry, we couldn't find any results matching
Please:

Key takeaways
The U.S. multifamily sector is downshifting from a period of strong demand growth from 2016–2024. During that time, a unique combination of elevated household formation driven by strong economic growth, the pandemic, fiscal stimulus, and a surge in immigration supported rental demand. Together, these forces drove above-trend absorption and rent growth across most markets, particularly in high-growth Sun Belt metro areas. Private residential investors realized strong returns, with NCREIF reporting unlevered returns of 19.4% in 2021, the strongest calendar year on record.1
The rise in interest rates in 2022, as well as slowing household formation, has changed the picture. As a result, the difference in household growth between Sun Belt and gateway markets has narrowed. Markets like Austin, Dallas, and Denver saw annual population growth 2.1 percentage points higher than New York City and Chicago from 2017-2024.2 The annualized growth gap has since narrowed to 1.1 percentage points, and we expect it to stay at that level until 2028 before Sun Belt market growth meaningfully outperforms again.
With demand growth converging across cities, supply has taken over as the key performance differentiator. Today we believe investors are being too quick to “price through” the current supply overhang in some Sun Belt markets, with some of the highest-quality high-rise apartments in Austin transacting at cap rates below 4.3%.3 Investors may also be too negative on the near-term performance of markets with high supply barriers, like New York and Chicago.
Demand outlook: below-trend household formation ahead
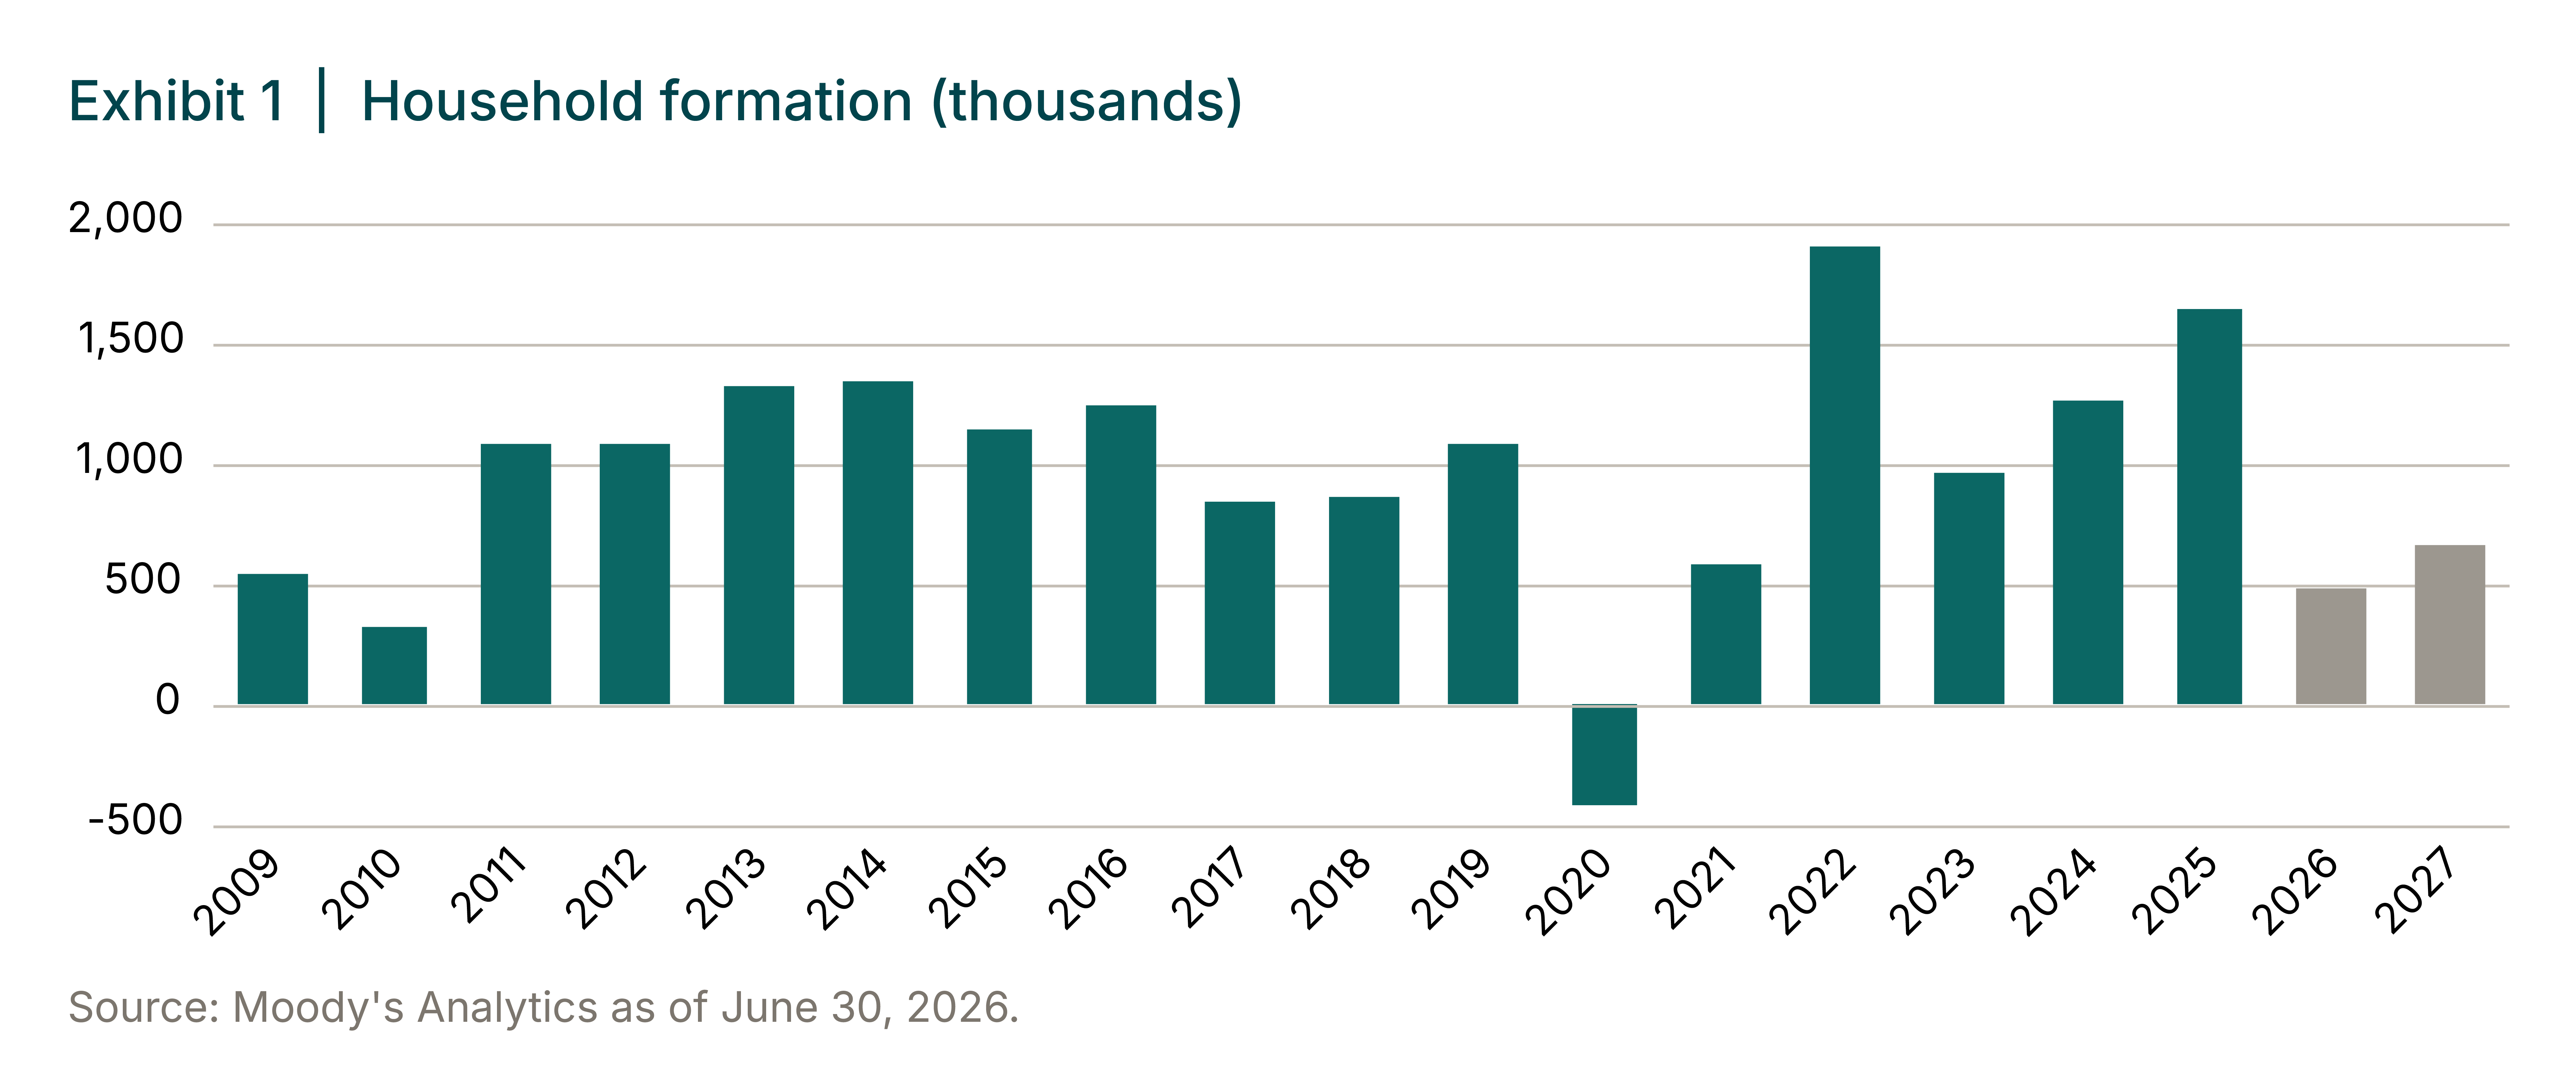
Household formation is set to slow dramatically from the 2017-2024 pace, and especially from the 2022-2024 pace when growth averaged nearly 1.4 million net new households per year. In 2026 and 2027, we expect around 583,000 net new households per year, a decline of roughly 58%. Sun Belt locations may feel the decline more than gateway and Midwest markets. There are three main reasons household formation is set to decline.
First, the impact of COVID-era fiscal stimulus has largely dissipated. From 2020 through mid-2021, households accumulated $2.3 trillion in savings from government transfers and constrained spending.4 This supported higher rates of household formation in 2021 and 2022, particularly among younger renters. With those supports now behind us, affordability constraints are likely to become more binding, limiting incremental demand from lower- and moderate-income households.
Second, a portion of demand was likely pulled forward during the pandemic. Remote work, school closures and lockdowns increased demand for housing space and appear to have raised household formation rates.5 Meanwhile, pandemic-era migration across cities gave birth to “Zoomtowns” and boosted absorption in many lower-density and high-growth markets. While migration supported near-term demand, it also likely shifted some future household formation forward, particularly in markets that experienced outsized in migration during 2021–2022.
Finally, immigration has slowed, shutting off an important source of recent demand. During the 2022–2024 surge, net immigration averaged 3 million people per year. In 2025, that number fell to 400,000.6 While we expect a modest recovery in authorized and temporary flows, bringing immigration to 600,000 people per year in 2026 and 2027, overall immigration will remain a fraction of prior levels.
Taken together, these factors point to a period of below-trend household formation. Even in historically strong growth markets such as Phoenix, Atlanta, and Dallas, we expect residential demand to moderate toward or below long-term averages.
Supply outlook: COVID winners are facing the toughest headwinds
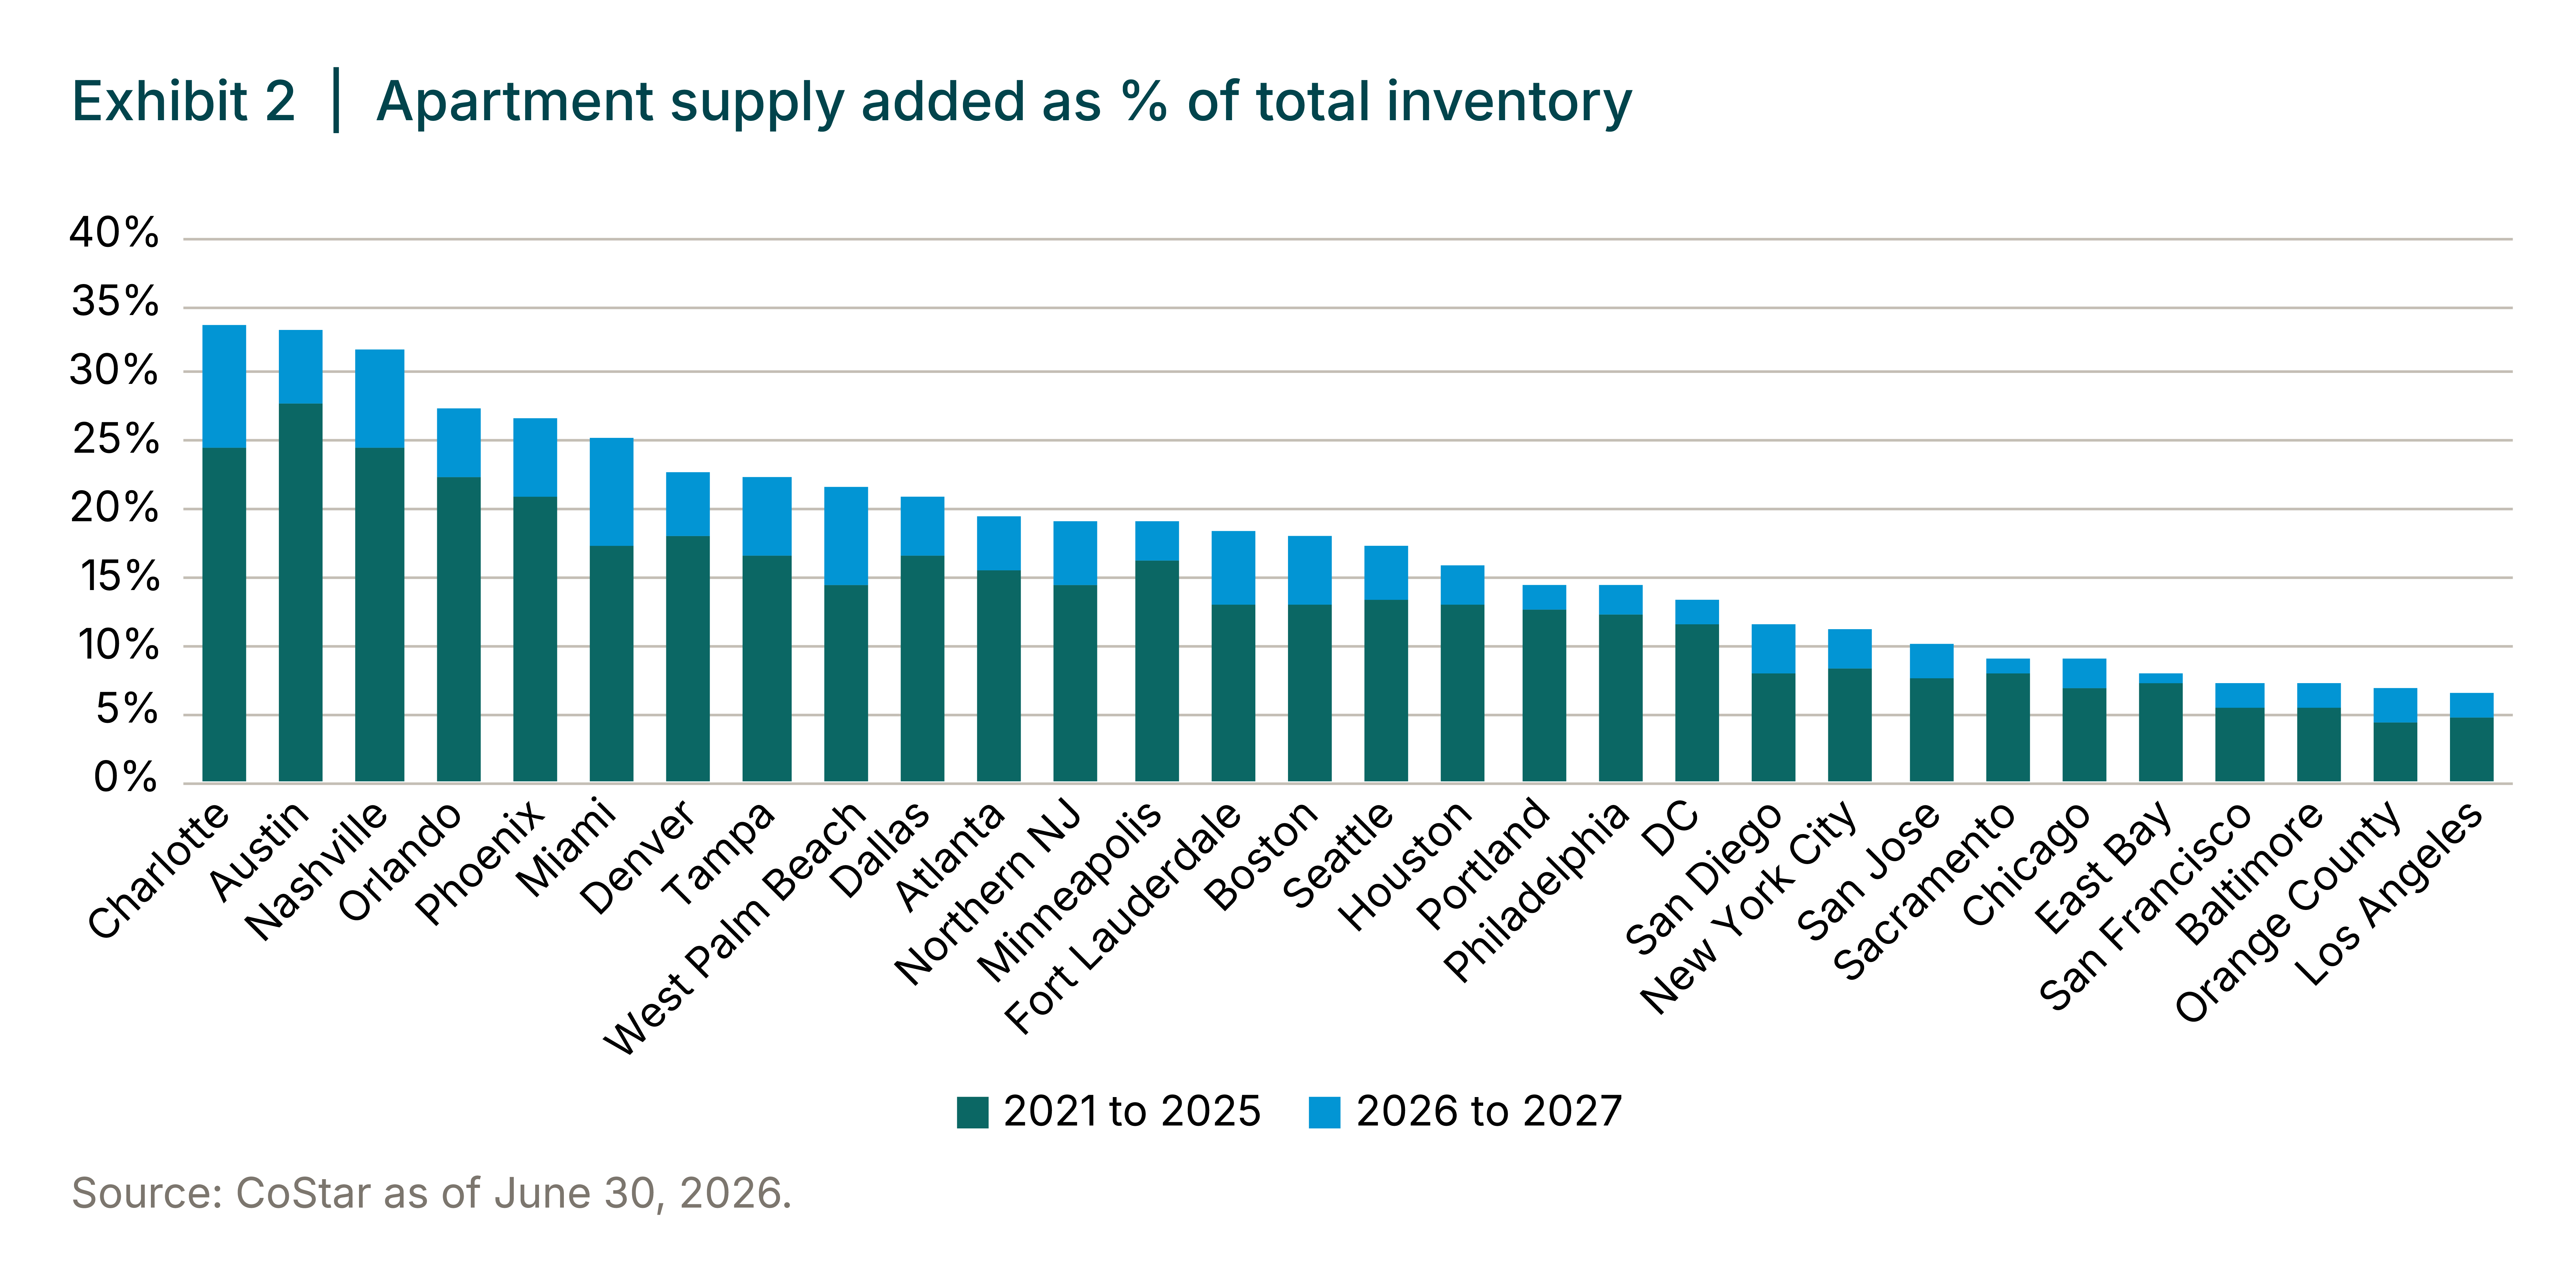
Going forward, supply conditions are likely to remain the primary differentiator of rental housing performance across cities. Some multifamily markets are working through a supply wave that resulted from a surge in construction starts in the years before 2023. Starts have since collapsed, as higher interest rates made the economics of development less profitable.
This expansion has been uneven across markets. Developers added supply most aggressively in metro areas that both experienced strong pandemic-era in-migration and faced relatively few regulatory constraints, resulting in wide dispersion in vacancy across cities. In our view, these markets are likely to continue to see elevated deliveries relative to other markets, which should keep vacancy elevated and delay rent recovery over the near-to-medium term.
A number of markets such as San Francisco, Chicago, and New York have substantial physical or regulatory barriers to new construction, while others, like Minneapolis, have seen construction starts collapse. These cities have average vacancies today that are at or below their “structural vacancy rates”, or the vacancy level at which market rents grow in line with inflation. We expect these markets to see some of the highest levels of rent growth in 2027 and 2028.
Putting it all together
Downshifting demand and uneven supply dynamics have created a complicated picture for investors. Some markets have stable rent growth and high supply barriers, but poor demographic traits. Others are experiencing elevated vacancy and weak rent growth, but with the promise of a strong recovery over the medium to long term.
Exhibit 3 attempts to quantify these dynamics. First, the table shows each market’s current vacancy rate compared to its structural vacancy rate. We show an estimate of when a given market is expected to return to its structural vacancy rate given local supply and demand dynamics.
Next, we translate the vacancy outlook into forecasts for near-term Net Operating Income (NOI) growth, which incorporates changes in market vacancy, rent, and expenses.
Finally, we make minor adjustments to the residual value calculation for high-growth markets that are more distressed today and pricing at a steeper discount to replacement cost. We expect shuttered supply pipelines in markets such as Austin, Phoenix, and Nashville to generate excess rent growth in the medium to-long term, which should result in more attractive multiples that a next buyer would pay for the same asset.
In the right-most column of Exhibit 3, we show the results of applying cap rates for average A/A- quality assets to these cash flow projections to produce an estimated 10-year internal rate of return (IRR) for each city that we believe is representative of current market underwriting.
In general, MIM prefers multifamily markets towards the top of this list, where our analysis shows the most promising opportunities. Those markets exhibit a healthier vacancy profile today, have favorable prospects for near-term rent growth, and as a result of those two factors, lower downside risk. Unusually, many of the markets with the strongest near-term rent growth prospects also trade at higher starting cash yields (cap rates)—the opposite of the typical pricing relationship—further boosting the return profile of healthier markets. We attribute this to the fact that many of the markets performing well today were underperformers in recent years due to slower demographics, and are still being penalized by investors.
There are a small handful of markets like Orange County and New York City where our analysis shows lower return opportunities, but vacancy and supply pipelines are also low today, significantly limiting downside risk. While we don’t believe those markets offer the best absolute returns today, they may offer attractive risk-adjusted returns.
Alternatively, markets like Austin, Denver, and Charlotte have a longer road to recovery, and while we believe the long-term prospects are strong, we think the right entry point may still be a year or two away so long as pricing stays where it is today. It’s possible, and even probable, that cap rates will not start increasing in those markets, and we do not believe investors are being compensated for the “catch a falling knife” risk that a new equity acquisition carries today. For debt investors, however, those markets may already be at an attractive entry point for low- or moderate-yield debt investments.