Are you planning to enroll in a dental or health insurance plan during an upcoming enrollment period? If so, you’ll likely receive either a digital or printed insurance card. Insurance cards contain important information, provide proof of insurance, and help ensure you’re charged the right amount for care. They also help your providers keep your insurance information up to date. Here are some helpful tips for how to read an insurance card.
Your insurance card contains important information about your plan, coverage, and whom to contact for help. Understanding what’s on your insurance card and how to read it is part of insurance literacy basics, and it can help you make the most of your benefits.
Understanding your health insurance can be complicated. That’s why spending some time to improve your insurance literacy is so important. After all, learning about your policy’s coverage and benefits can help you plan your and your family’s care and save money in the process.1
What’s on your insurance card can give you some key pieces of information you can refer to each time you see a provider. But it can be challenging, because many cards contain insurance terminology and abbreviations that are difficult to understand. Not to worry: We’ve broken down all the parts of an insurance card so you can find the information you need.
Here’s an example of what you might typically find on an insurance card:
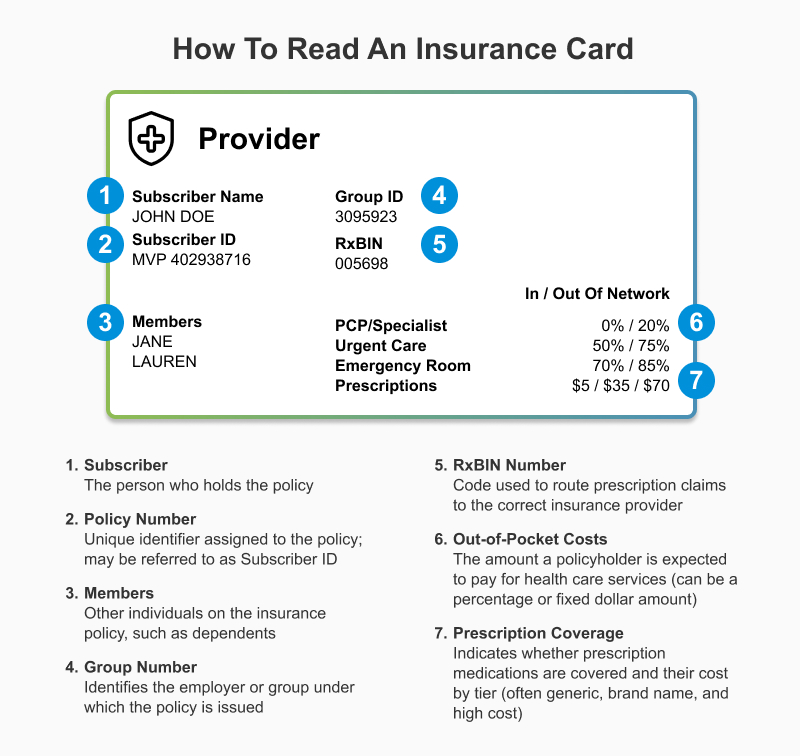
The main sections of an insurance card are typically right on the front. Here, you will find:2
Personal information
Most insurance cards include your name and policy number. If you're covered under your spouse’s or parent's plan, your card may include their name, too.
Member ID or policy number
The policy number on your insurance card is a unique code associated with your insurance plan. Your insurance company uses your policy number to track and process insurance claims and costs. The Policy number may also be referred to as “Subscriber ID” or “Member ID” number, or as a “Policy #” or “Policy ID.” If you’re unable to locate your policy number, reach out to your insurance provider for assistance.
Plan type
You card may show whether you have an HMO (health maintenance organization), PPO (preferred provider organization, or POS (point of service) plan.
Members
This a list of other members of your family who are covered under the policy.
Insurance group number
If you have insurance coverage through an employer, your insurance card will likely have an insurance group number, also known as a group plan number.
Like your individual policy number on an insurance card, the group number on your insurance card is a code assigned to your employer’s insurance plan. Your insurance group numbers help insurance companies identify the benefits included in your employer’s plan and process claims effectively.
RxBIN code
The RxBIN code helps direct prescription claims to the right insurance provider. They make it easier for healthcare providers, clinics, hospitals, and pharmacists to identify your insurance carrier and submit claims.
In-network and out-of-network coverage
Your insurance card may list two coverage percentages for in-network or out-of-network providers. In-network providers are those who have a contractual agreement with your insurance company to provide lower-cost services and treatments.
Visiting an in-network provider often results in lower expenses compared to visiting an out-of-network one. For most plans, you can still see an out-of-network provider if you choose to do so. However, you’ll likely pay more for out-of-network care. Contact your provider for more information on in-network and out-of-network providers, along with the costs associated with each.
Coverage and copay amounts
The coverage amount refers to how much of your healthcare costs your insurance company will pay for your care. You can usually find this information on the front of your insurance card. Coverage amount numbers may be listed as fixed dollar amounts or percentages, such as 25%, 50%, or 75%. Often, several amounts are listed together and may correspond to different types of treatments or office visits. You may also see additional information regarding copays and in-network or out-of-network care.
A copay is a fixed dollar amount you’re required to pay out-of-pocket for certain types of care or treatments. Also known as a copayment, copays vary based on the type of plan you have, the kind of treatments you receive, and whether you use an in-network or out-of-network provider. You can typically find copays listed on the front of your insurance card.
Depending on the type of insurance policy you have, your provider may pay for some or all of the cost of prescription medications. In this case, you may find an Rx category on your insurance card. Not all cards have an Rx category. If yours does, it’ll list the dollar amount or percentage your insurance company will pay for each prescription. If not, you can contact your insurance company to learn more about coverage and associated costs.
On the back of your insurance card is usually find information about your insurer, including their address and phone numbers for members are providers.2 This information is useful to have in case you need to:
- Ask questions about your benefits and coverage
- Find an in-network provider
- Determine if a service or treatment is covered by your policy
Are you a MetLife member? Depending on the kind of coverage you have, your insurance card will feature different pieces of information. For instance, if you have MetLife dental insurance, your card may have the following features (keep in mind the card can vary since different plans offer different types of coverage):
MetLife ID or Subscriber Number
Your Member ID or Subscriber ID is typically located on the front of your MetLife dental ID card. You can also access this information by logging in to your MyBenefits account or through the MetLife mobile app, where you can view, download, or print your digital ID card. If your employer provides a MetLife Alt-ID, that is the number you will see. Often, your ID number will be your Social Security number, in which case it will not be shown.
Where is the MetLife policy number located?
The policy number, if displayed, is generally found on the front of the card near the member or group information section. Depending on the employer-sponsored plan, some cards may instead display a group number and subscriber/member ID rather than a policy number.
What is the MetLife Subscriber ID and how is it used?
The Subscriber ID, also referred to as a Member ID, is the unique identification number assigned to the enrolled member. Dental offices use this number to verify eligibility, review benefits, and submit claims.
What is the group number on a MetLife insurance card?
The group number identifies the employer-sponsored plan under which a member is covered. It helps MetLife and participating providers determine the specific benefits, coverage provisions, and network information associated with the member's plan.
What is the RxBIN number and why is it important?
An RxBIN number is used for processing prescription drug claims. While many dental-only ID cards do not include an RxBIN number, it may be present when prescription benefits are associated with the plan. Pharmacies use the RxBIN number to route prescription claims to the correct prescription benefit administrator.
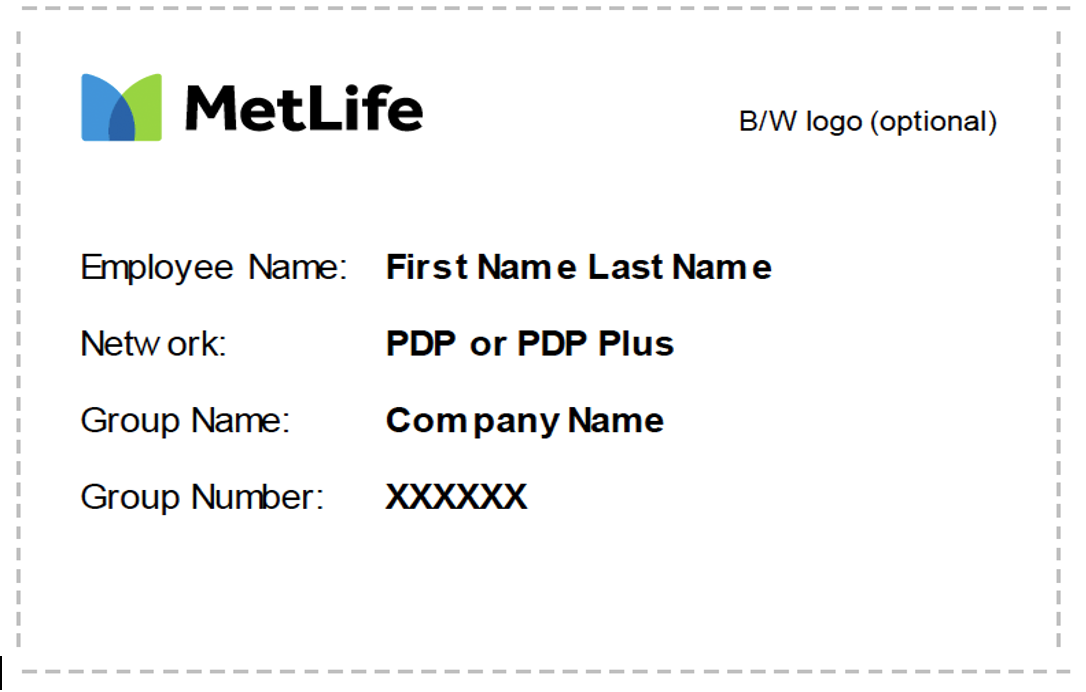
Here is a sample of the front of a MetLife dental insurance card:
Some of the most common terms you’ll see on an insurance card are:2
PPO, HMO, PPO: This indicates the type of insurance plan you have—a health maintenance organization, preferred provider organization, or point of service plan.
GRP: This shows what your insurance plan group number is.
ID: This is your individual member ID number.
PCP: Short for “primary care provider.” The dollar amount associated with it indicates your co-pay for primary care doctor visits.
Specialist or SPC: The dollar amount associated with this indicates your co-pay for when you see a specialist (”SPS” stands for “specialist care provider”).
ER or emergency: The dollar amount associated with this, which stands for “emergency care,” shows your co-pay for ER visits.
Urgent or urgent care: Your card may also show what your co-pay will be for urgent care visits.
Rx or prescription: This helps you understand your co-pay or co-pays for medications.
RxBIN: This is an insurance code that’s used to prescription claims.
In-network/Out-of-network: This differentiates how much your co-pays are when you see a provider that is in-network versus out-of-network. In-network means the provider is contracted with your insurer to provide services, and out-of-network means the doctor does not have a formal contact with the insurer. You may also see “In” and “IN” for in-network or “OON” for out-of-network.
The terms on an insurance card can help you plan what some of your costs may be when you see a doctor or dentist. If you have questions about any of the terms, contact your insurance company.
Always bring your insurance card with you when you go to a doctor’s or dentist appointment, and be prepared to show it when you check in. It’s a good idea to have your card with you even if your insurance hasn’t changed, or if you check-in already online.
Bring your card with you when you pick up a prescription as well, in case the pharmacy needs to check anything with your policy, or in case you need to call your insurer to ask any questions about costs.
It’s always a good idea to use the insurance provider contact information on your card to contact your insurer before your doctor’s or dentist appointment, or before you pick up a prescription — explain what your visit or prescription is for, and ask what the costs, such as co-pays or co-insurance, may be. Ask if you’ve met your deductible, and get an estimate for what your total out-of-pocket costs could be.
You can lower your costs by seeing an in-network provider, rather than an out-of-network one, as insurance companies often negotiate more favorable rates with their in-network providers.2
If you have to go to the emergency room, be sure to bring your insurance card, and notify your insurer ahead of time if you can. Whatever type of provider you plan to see — a doctor, specialist, hospital, dentist, etc. — if possible, check with your insurer about the possible costs beforehand, and get a pre-authorization if needed.2
One way to tell if you have prescription drug coverage is to check your insurance card. It may have a quick reference — usually labeled as “Rx” — for how much your co-pay, or out-of-pocket cost, is for prescription drugs. If your insurance has different pricing for different types of drugs, you might find a few different amounts on your card. Check with your plan to see what your co-pay if for a specific drug.2
Your card may also have an “RxBIN” number. That’s not an indication of any out-of-pocket costs, but rather an insurance code that your pharmacy can use for filing claims.
Other out-of-pocket costs could include your deductible or co-insurance. These amounts may appear on your card as well, but check with your insurer beforehand to get estimates so you won’t be surprised at the pharmacy.
What to do if you lose your insurance card? Contact your insurer to let them know, and ask for a replacement card.
If you have an appointment coming up and haven’t received your card yet, get your member ID and group number by logging into your account online, so you can provide this information when you check in for the office to verify. Some insurers may offer digital IDs that you can get when you download their app.3
If you are a MetLife member, and you find that information on your insurance card is incorrect, follow these steps:
- Review your enrollment information.
- Contact MetLife Customer Service for assistance. You can find the phone number on the back of your insurance card, by logging on to MyBenefits, in the MetLife mobile app, or on MetLife.com.
- Request an updated ID card once the correction has been processed.
You can follow similar steps to report a lost or stolen MetLife insurance card:
- Log in to your MyBenefits account to access a digital version of your ID card.
- Contact MetLife Customer Service if you believe your information may have been compromised.
- Request a replacement ID card.
- Verify that your mailing address and contact information are current before the replacement card is issued.
To request a replacement MetLife card and update your information, do the following:
- Sign in to your MyBenefits account.
- Access your dental benefits information.
- View or download your digital ID card immediately.
- Contact MetLife Customer Service to request a replacement physical card, if available for your plan.
- Update your personal information through the appropriate enrollment or benefits administration channel. Members can also access plan information, claims, and ID cards through MyBenefits and the MetLife mobile app.
Understanding the information on your insurance card is one way to improve your insurance literacy, as it contains important details about what your plan covers, how much you can expect to pay out of pocket, and how to contact your insurer for help.
Whether you have MetLife insurance, or insurance from another provider, take the time to understand what is on your insurance card, and be sure to use it each time you visit a provider. If you can, check with your insurer before you go for a visit, to get an estimate of costs, or get a pre-approval.
If there are terms or abbreviations you don’t understand, contact your insurance provider for help. Your individual card may contain additional information to what is typically found on insurance cards.